First-Time Buyers
Builder Incentives Look Attractive. Here’s How to Compare the Real Value
A rate buydown, closing-cost credit, and price cut can look similar in an ad but deliver very different long-term value.
TL;DR
- • New-home supply was 8.4 months in September 2026, giving some builders reason to compete for buyers.
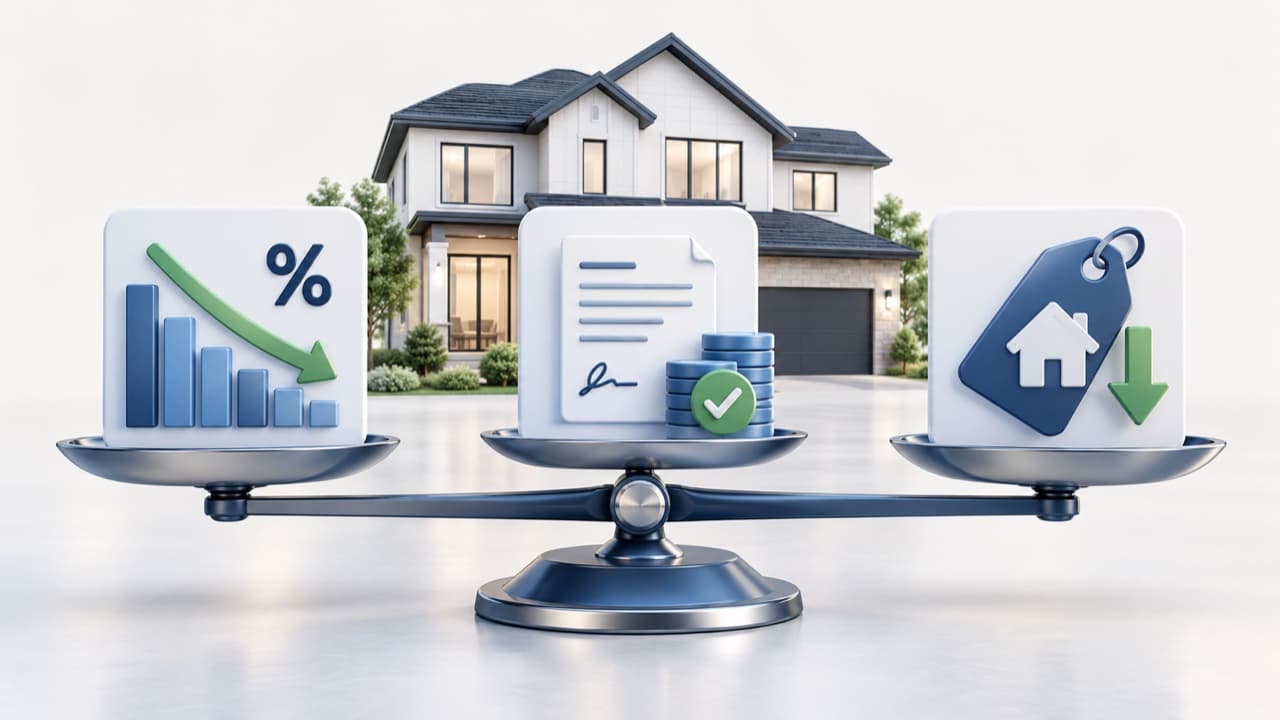
- • A rate buydown, closing-cost credit, and price reduction solve different problems.
- • Compare offers on the same time horizon and include the incentive's conditions.
Why incentives deserve attention now
The Census Bureau estimated 676,000 new-home sales at a seasonally adjusted annual rate in September 2026, down 5.3% from a year earlier. There were an estimated 476,000 new homes for sale, equal to 8.4 months of supply at the current pace.
That does not mean every builder will negotiate, but a larger supply can encourage incentives on certain communities, completed homes, or fiscal-year deadlines.
Three common incentives are not interchangeable
A permanent rate buydown uses upfront money to reduce the rate for the loan term. A temporary buydown lowers the payment only during the first years. A closing-cost credit reduces cash needed at closing, while a price reduction lowers the purchase price and loan amount.
A headline dollar amount can hide different long-term value. The best choice depends on how long the buyer expects to keep the loan, available cash, and whether the incentive requires the builder's preferred lender or title company.
How to compare the real value
Ask for a Loan Estimate for each option on the same day. Compare cash to close, principal and interest, total monthly payment, APR, points, lender fees, and the payment after any temporary buydown expires. Then calculate the break-even period.
- Price the home without incentives as a baseline.
- Confirm whether unused credits are lost.
- Inspect the home as carefully as a resale property.
- Compare the preferred lender with at least one outside lender.
AffordSimple calculator
Compare cash to close
Model the down payment, lender and seller credits, closing fees, and prepaid costs before choosing an incentive.
Estimate cash to close →Bottom line
Builder incentives can create real value, especially for cash-constrained buyers, but only after an apples-to-apples comparison. Choose the option that improves the full budget over the period you realistically expect to own the loan.
Sources and methodology
Market figures are sourced from the publications below. Examples are illustrative and are not loan quotes or financial advice.